
Business finance
Commercial property finance: separate the building from the business
Prepare for commercial property finance in NZ by reviewing occupancy, property costs, lease details and the business cash-flow impact.

Written by Eric Huang
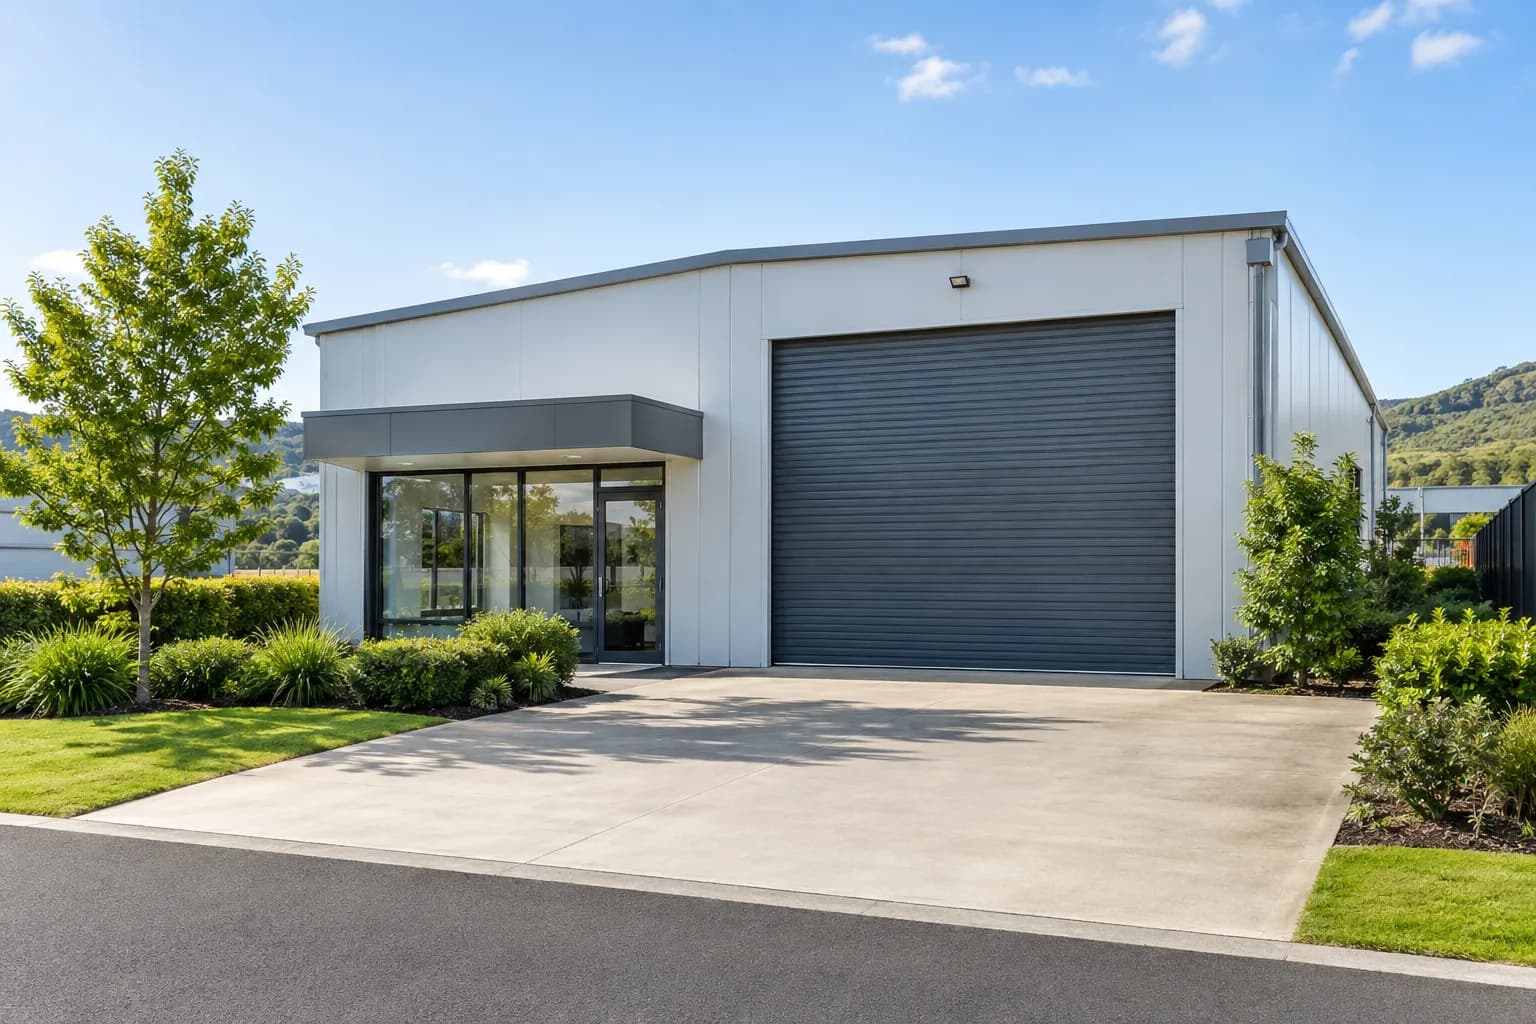
Buying premises can give a business more control over its location, but it also ties capital to a property. Assess the building as an asset and the operating business as a source of cash, even when they share an owner.
Clarify the purpose
Will your business occupy the property, or will it be leased to another tenant? The evidence needed can differ. Prepare a clear description of the proposed use and ownership structure. Ask your accountant and lawyer about tax and legal implications rather than copying another buyer's setup.
Business.govt.nz recommends considering the opportunities and constraints of both buying and leasing premises. Buying is not automatically better if it leaves insufficient cash for the business itself.
Look beyond the purchase price
Budget for due diligence, valuation, legal work, insurance, maintenance, fit-out and any required compliance work. Have relevant professionals assess building condition and permitted use. Get advice on GST and settlement treatment; do not assume residential purchase rules apply.
Examine the income or occupancy case
For a leased investment, review the lease, tenant position, expiry dates, renewal rights and responsibility for outgoings with your lawyer. For owner-occupation, test whether the operating business can meet property and finance costs while maintaining working capital.
Prepare questions for the lender
- What deposit, valuation and financial evidence are required?
- What loan term, repayment schedule and review conditions apply?
- Are guarantees or additional security requested?
- What happens if the premises are vacant or the business slows?
Our commercial loan service can discuss the financing structure. Use the business application checklist to prepare records, and keep independent legal and accounting advice central to the transaction.
Sources & further reading
General information only, not personalised financial, legal or tax advice. Lending criteria, fees and terms apply and can change. Discuss your circumstances with an appropriately qualified adviser before making a decision.
Your next step
Keep reading
A practical business loan application checklist for NZ owners
Prepare a business finance application with a defined purpose, financial records, realistic forecasts and a clear repayment plan.
Investment property cash flow: look beyond the weekly rent
Create a practical NZ rental property cash-flow plan covering vacancy, repairs, insurance and debt repayments before considering finance.