
Property & building
Construction loans in NZ: planning progress payments
Understand construction loan drawdowns, builder payment stages and budget buffers before starting a New Zealand home build.

Written by Eric Huang
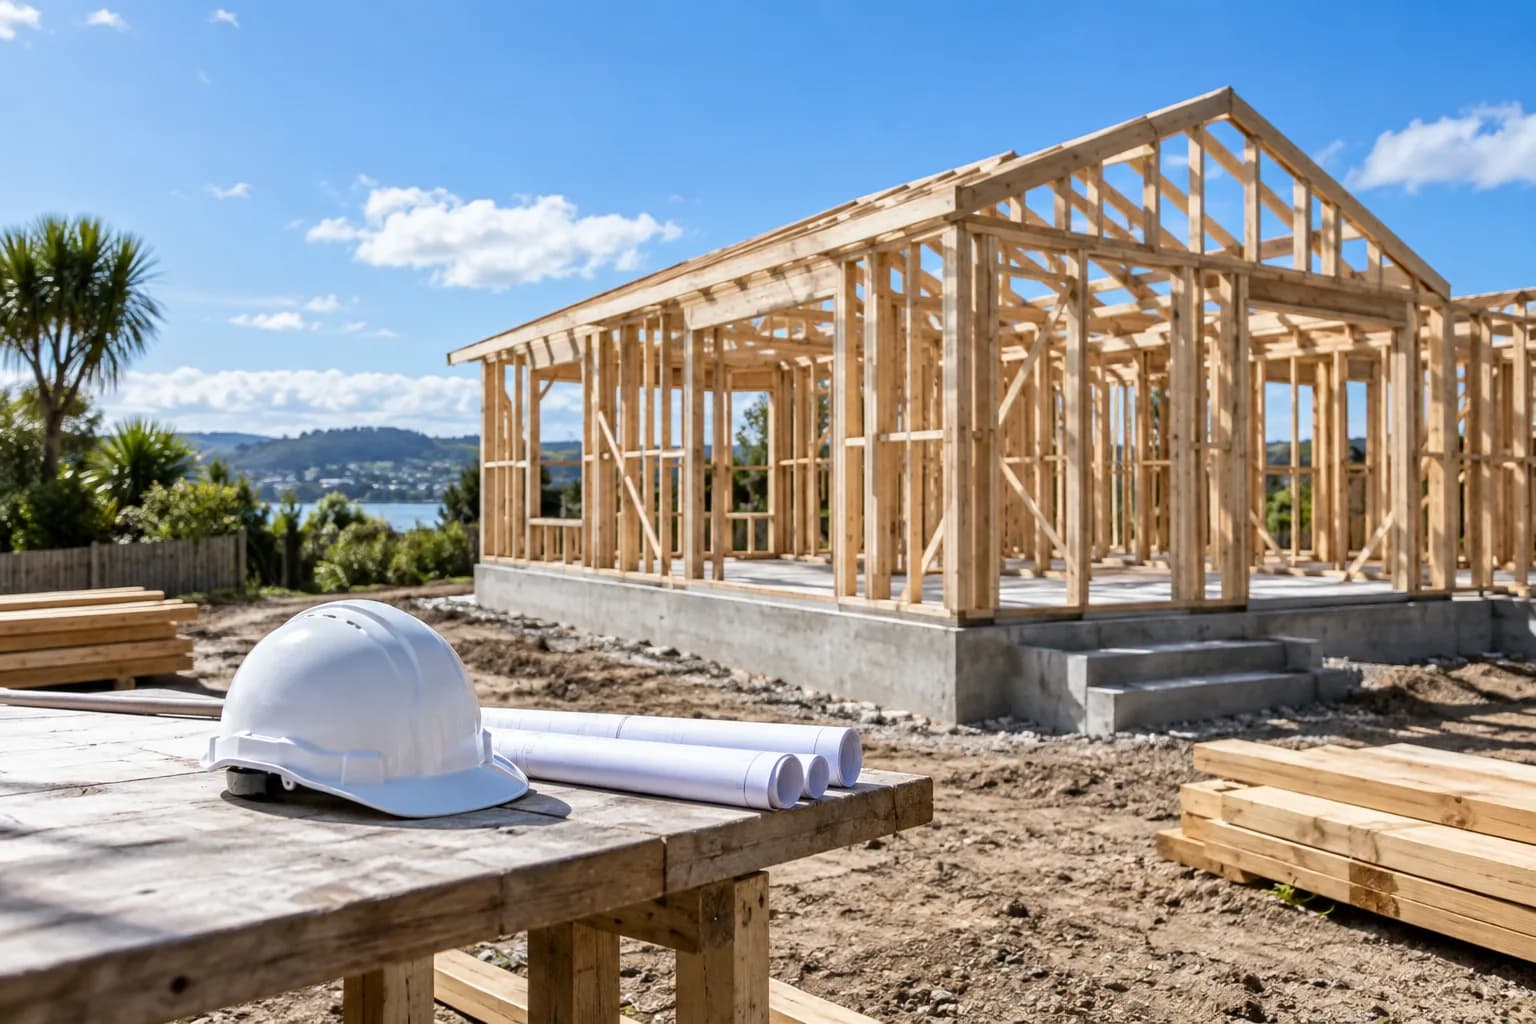
A construction budget needs a timetable as well as a total. A lender's approved facility does not necessarily mean the entire amount is immediately available to pay a builder. Funding is commonly released in stages under agreed conditions.
Align the contract and loan schedule
Ask the builder, lawyer and adviser to help you compare the contract's payment milestones with the lender's release requirements. Find out what evidence, inspections or valuations are needed at each stage. Allow processing time between a payment request and the builder's due date.
Budget beyond the headline build price
Record what the contract includes and excludes. Site work, professional fees, connections, landscaping and variations can change the total. Keep a realistic contingency and ask how additional costs would be funded. A higher build cost does not automatically create more borrowing capacity.
During construction you may also have rent or an existing mortgage to pay. Model the overlap and the interest on funds drawn over time, using the proposed lender's actual structure rather than assuming every construction product works identically.
Manage changes before agreeing to them
Keep variations written and priced. Check the effect on timing, remaining funds and lender approval before authorising extra work. An appealing upgrade can be difficult to finance once the original budget is committed.
Before the final drawdown
- Confirm completion evidence and any lender conditions.
- Check insurance arrangements as the property moves into occupation.
- Reconcile outstanding invoices with remaining funds.
- Discuss the repayment structure after construction.
Our construction loan service can help coordinate the finance side. For a smaller project on an existing home, read about renovation top-ups.
Sources & further reading
General information only, not personalised financial, legal or tax advice. Lending criteria, fees and terms apply and can change. Discuss your circumstances with an appropriately qualified adviser before making a decision.
Your next step
Keep reading
Renovation finance: questions before a home loan top-up
Consider renovation costs, equity, affordability and repayment length before using a New Zealand home loan top-up for improvements.
A first-home deposit is not your whole buying budget
Build a realistic NZ first-home budget with separate amounts for your deposit, purchase costs and a post-settlement emergency buffer.